A CashNetUSA loan may show an interest rate or APR in the agreement, but that number does not always reveal the complete cost of borrowing. For certain active-duty service members and qualifying dependents, the Military Lending Act places limits on the cost and terms of covered consumer credit.
CashNetUSA offers regular consumer credit to the public. It does not need to market or describe an account as a “military loan” for the Military Lending Act to apply. The important questions are whether the person was a covered borrower at the relevant time and whether the transaction qualified as covered consumer credit.
A CashNetUSA Military Lending Act review is not limited to the stated interest rate or standard annual percentage rate. It may require calculating the Military Annual Percentage Rate, commonly called MAPR. It may also require reviewing the disclosures and other terms of the agreement.
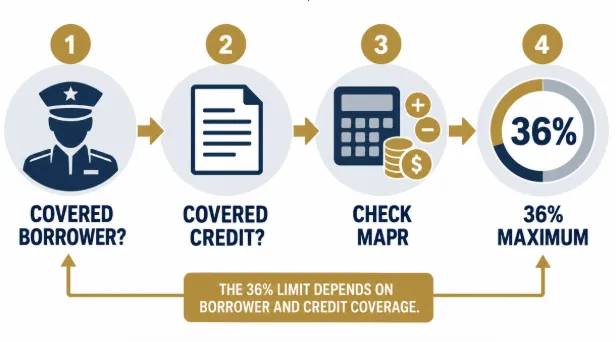
The MLA generally prevents a creditor from imposing an MAPR above 36% on covered consumer credit extended to a covered borrower. Determining whether a particular CashNetUSA account falls under that rule can take several steps.
At Varnell & Warwick, we believe borrowers should understand which records and facts matter. This article provides general information and does not decide whether CashNetUSA or any other creditor violated the law in a specific case.
Key Takeaways
- CashNetUSA provides regular consumer credit, not a special military lending product.
- The MLA may apply when covered credit is extended to a servicemember or another covered borrower.
- Covered consumer credit generally cannot have an MAPR above 36%.
- APR, interest rate, and MAPR are not necessarily the same.
- MAPR may include certain fees and credit-related products.
- The borrower’s covered status at the relevant time is important.
- Not every transaction involving a servicemember is covered.
- The agreement, statements, fees, military records, and account-opening date may all matter.
What Is the Military Lending Act?
The Military Lending Act, or MLA, is a federal law that limits the cost and terms of certain consumer credit extended to covered members of the armed forces and their qualifying dependents.
A covered member generally includes someone serving on qualifying active duty under Title 10, 14, or 32 pursuant to an order that does not specify a period of 30 days or fewer. It may also include someone serving on Active Guard and Reserve duty.
Certain spouses, children, and other dependents may qualify as covered borrowers as well.
The MLA does not apply simply because someone served in the military at some point. Covered status generally matters when the person becomes obligated on the transaction or establishes the credit account.
That timing is an important part of any CashNetUSA Military Lending Act review. Borrowers should compare the date the account was opened with military orders or other records showing their status at that time.
The Department of Defense’s current definitions and coverage rules appear in 32 C.F.R. §§ 232.2 and 232.3.
What Is the MLA’s 36% MAPR Limit?
The MLA generally prohibits a creditor from imposing an MAPR above 36% on covered consumer credit extended to a covered borrower. For closed-end credit, the limit applies to the extension of credit. For open-end credit, it applies during each billing cycle.
MAPR can include more than the ordinary interest rate. Depending on the transaction, it may include:
- Interest and finance charges
- Credit insurance premiums or fees
- Debt-cancellation fees
- Debt-suspension fees
- Fees for credit-related add-on products
- Certain application fees
- Certain participation fees
The rules contain limited exceptions. For example, some reasonable and bona fide credit card fees may be excluded under specific conditions.
Because MAPR can include costs beyond ordinary interest, it may be higher than the standard APR shown in an agreement. The regulation describing the 36% limit and included charges appears in 32 C.F.R. § 232.4.
Does the MLA Apply to Every CashNetUSA Loan?
No. The fact that a servicemember received a CashNetUSA loan does not automatically mean the MLA applies. It also does not automatically mean the law was violated.
A proper review should answer two basic questions:
- Was the borrower a covered borrower at the relevant time?
- Was the transaction covered consumer credit?
The MLA generally covers credit offered or extended primarily for personal, family, or household purposes when the credit is subject to a finance charge or payable under a written agreement in more than four installments.
Depending on the facts, covered credit may include certain installment loans, lines of credit, payday loans, vehicle title loans, credit cards, and other consumer credit products.
The law also contains exceptions. These generally include:
- Residential mortgages
- Home equity loans and lines of credit
- Mortgage refinancing
- Credit expressly intended to finance the purchase of a motor vehicle when the vehicle being purchased secures the credit
- Credit expressly intended to purchase personal property when that property secures the transaction
The transaction’s name does not provide the full answer. Its purpose, structure, payment terms, and security interest may all need to be examined.
Step 1: Confirm Covered-Borrower Status
Begin with the date the account was opened or the date the borrower became obligated on the transaction. Then gather documents showing military or dependent status at that time.
Useful records may include:
- Active-duty orders
- Leave and earnings statements
- Records showing the dates of qualifying service
- Marriage records
- Dependent-status records
- Other official military documentation
Creditors are permitted to determine covered-borrower status through their own methods. The regulation also provides safe-harbor methods involving the Department of Defense database or a qualifying indicator from a nationwide consumer reporting agency.
However, the main question for the borrower is not simply whether the application included military questions or whether a particular database was used. The review should determine whether the person actually had covered status at the relevant time and whether the creditor may rely on a regulatory safe harbor.
A CashNetUSA Military Lending Act issue should not be accepted or rejected based on guesswork about military status.
Step 2: Gather the Complete Account Records
A payment receipt or current balance is usually not enough to evaluate the account.
Try to gather:
- The original application
- The credit agreement or promissory note
- Account-opening disclosures
- Truth in Lending disclosures
- Payment schedules
- Monthly statements
- Transaction histories
- Documents for renewals or refinancing
- Records of fees
- Documents for credit insurance or add-on products
- Emails, text messages, and account notices
- Bank records showing the amount received
- Records showing the total amount repaid
If the account remains accessible online, download the original files when possible. Screenshots may also help, but original PDFs and complete statements are usually easier to organize and review.
Keep the files unchanged. Make separate notes rather than writing on the originals.
Step 3: Separate Interest, APR, and MAPR
Interest, APR, and MAPR are related, but they do not always mean the same thing.
The interest rate generally describes the percentage charged for borrowing the principal. APR is calculated under general consumer credit rules and normally includes the interest rate plus certain finance charges.
MAPR is the annual cost measure used under the Military Lending Act. It may include additional fees or credit-related products that are not counted in the ordinary APR in the same way.
Imagine that an account includes interest plus a fee for a credit-related add-on product. The regular APR may reflect the interest and certain finance charges. The MAPR calculation may also need to include the add-on fee.
This does not mean every fee automatically counts. The type of credit, purpose of the charge, and way it was imposed all matter.
A careful CashNetUSA Military Lending Act evaluation should follow the proper MAPR calculation rules. Simply multiplying a fee by the number of payment periods may produce an inaccurate result.
Step 4: Look for Charges Beyond Interest
Review the agreement and statements for charges such as:
- Application fees
- Participation fees
- Membership fees
- Credit insurance
- Debt cancellation
- Debt suspension
- Ancillary credit products
- Service charges
- Account-opening charges
- Renewal-related charges
Some charges may have been deducted before the funds reached the borrower. For example, an agreement might list one amount while a smaller amount was deposited.
That difference does not automatically establish a violation. It may show that the transaction and its charges deserve closer examination.
The correct question is not only, “How much interest did I pay?” It is also, “Which costs must be included when calculating MAPR?”
Step 5: Review the Disclosures
For covered consumer credit, a creditor generally must provide certain information before or when the borrower becomes obligated on the transaction or establishes the account.
The required information generally includes:
- A statement describing MAPR and the charges that may be imposed
- Disclosures required under Regulation Z
- A clear description of the borrower’s payment obligation
An important detail is that the creditor is not necessarily required to disclose MAPR as a specific numerical value. The regulation allows a creditor to satisfy the MAPR-statement requirement by describing the charges that may be imposed.
The MAPR statement and payment-obligation information generally must also be provided orally. For an internet transaction, oral delivery may be completed through a toll-free telephone number that the borrower can use to hear the required information.
This means the disclosure review should consider both the written documents and how the oral information was made available. The disclosure rules appear in 32 C.F.R. § 232.6.
Step 6: Examine Other Contract Terms
The MLA’s protections are not limited to the 36% MAPR cap.
Depending on the transaction, the law generally restricts a creditor from:
- Requiring mandatory arbitration
- Requiring a covered borrower to waive certain legal rights
- Requiring repayment through a military allotment
- Charging a penalty for paying early
- Imposing certain unreasonable notice requirements before legal action
- Using certain prohibited forms of account access or security
An agreement may therefore need review even when the borrower cannot calculate MAPR. The account’s disclosures and contract terms should be considered together.
Warning Signs That May Deserve Review
No single warning sign proves that the MLA was violated. However, a closer review may be appropriate if:
- You were on qualifying active duty when the account was opened
- Your spouse obtained the credit while you were a covered member
- The agreement displayed a very high APR
- Fees or credit-related products increased the cost
- The amount deposited was lower than the amount stated
- The account was renewed, refinanced, or increased
- The agreement included mandatory arbitration
- You were required to repay through a military allotment
- You were charged for paying early
- You did not receive a clear explanation of your payment obligation
These facts may help identify useful questions. They do not replace a calculation of MAPR or a review of whether the MLA covered the transaction.
What If the Account Was Renewed, Refinanced, or Increased?
Renewals, refinancing, new advances, and credit-limit increases can make the analysis more complicated.
Each transaction may involve a different date, amount, fee structure, and repayment obligation. The borrower’s covered status may also have changed.
Do not review only the newest statement. Keep every agreement and create a timeline showing:
- When the original account was opened
- When each advance was taken
- When the credit limit changed
- How much money was received
- Which fees were charged
- How payments were applied
- Whether the borrower had covered status at each relevant time
Whether a later event counts as a new extension of credit can depend on the agreement and account structure. It should not be assumed without reviewing the documents.
What Remedies May Be Available?
The Military Lending Act provides possible civil remedies for certain violations. Depending on the facts, these may include actual damages, a statutory minimum recovery, appropriate punitive damages, equitable or declaratory relief, court costs, and reasonable attorney fees in a successful action.
The statute also provides that certain prohibited credit agreements may be void from the beginning.
These are possible legal remedies, not guaranteed results. Whether they apply depends on the borrower’s status, the type of credit, the timing, the charges, the terms, and the available evidence.
A borrower should not stop making payments or ignore collection notices based only on general information found online. That decision could create additional financial or legal problems. Individual legal guidance may be necessary.
How to Prepare for a Legal Review
If you believe your CashNetUSA account may exceed the MLA limit, prepare a folder containing:
- The original agreement
- Every renewal or refinancing agreement
- Account statements
- Proof of military or dependent status
- Bank records showing the amount received
- Records of payments
- Fee descriptions
- Add-on product documents
- Emails, text messages, and collection notices
- A timeline of the account and qualifying service
It may also help to write down what happened in your own words. Include how you applied, what you were told, which disclosures you received, and whether the account was later renewed or changed.
Do not alter the original records. Preserve the electronic files and their dates when possible.
Talk With Varnell & Warwick About Your CashNetUSA Account
Determining whether a CashNetUSA account exceeded the MLA limit involves more than reading the interest rate on the first page. It may require confirming covered status, identifying the credit product, reviewing disclosures, calculating MAPR, and examining the agreement’s other terms.
Varnell & Warwick can review information related to a possible CashNetUSA Military Lending Act issue and explain which facts may matter. Every situation is different, and no result can be promised before the records are examined.
Remember, the account does not need to be called or marketed as a military loan. CashNetUSA provides regular consumer credit to the public. The legal issue is whether covered consumer credit was extended to a covered borrower on terms that complied with the Military Lending Act.
If you or your qualifying dependent obtained a CashNetUSA account while protected by the MLA, gather the agreement, statements, fee records, and military-status documents. A detailed review may help determine whether further action is appropriate.
The purpose of a CashNetUSA Military Lending Act review is not to guess based on one percentage. It is to examine the full transaction and determine how the law applies to the specific facts.